Life is a math equation. In order to gain the most, you have to know how to convert negatives into positives, Anonymous.
Pure mathematics is, in its way, the poetry of logical ideas, Albert Einstein.
Recall: Vector Basics
Definition. A vector $\vec{AB}$ is a geometric object or quantity that has both magnitude (or length) and direction. Vectors in an n-dimensional Euclidean space can be represented as coordinates vectors in a Cartesian coordinate system.
Definition. The magnitude of the vector $\vec{A}$, also known as length or norm, is given by the square root of the sum of its components squared, $|\vec{A}|~ or~ ||\vec{A}|| = \sqrt{a_1^2+a_2^2+a_3^2}$, e.g., $\vert{}\vert{}\langle 3, 2, 1 \rangle\vert{}\vert{} = \sqrt{3^2+2^2+1^2} = \sqrt{14}$, $\vert{}\vert{}\langle 3, -4, 5 \rangle\vert{}\vert{} = \sqrt{3^2+(-4)^2+5^2} = \sqrt{50} = 5\sqrt{2}$, or $\vert{}\vert{}\langle 1, 0, 0 \rangle\vert{}\vert{} = \sqrt{1^2+0^2+0^2} = \sqrt{1} = 1$.
Basic Vector Operations
-
Vector Addition: The sum of two vectors is the sum of their components, $\vec{A}+ \vec{B} = (a_1+b_1)\vec{i}+(a_2+b_2)\vec{j}+(a_3+b_3)\vec{k} = \langle a_1+b_1, a_2+b_2, a_3+b_3 \rangle$.
-
Vector Subtraction: The subtraction of two vectors is similar to addition and is also done component-wise, it is given by simply subtracting their corresponding components (x, y, and z in 3D), $\vec{A} - \vec{B} = (a_1-b_1)\vec{i}+(a_2-b_2)\vec{j}+(a_3-b_3)\vec{k} = \langle a_1-b_1, a_2-b_2, a_3-b_3 \rangle$.
-
Scalar multiplication is the multiplication of a vector by a scalar, a real number, changing its magnitude without altering its direction (unless the scalar is negative, which reverses the direction). It is effectively multiplying each component of the vector by the scalar value, $c\vec{A} = (ca_1)\vec{i}+(ca_2)\vec{j}+(ca_3)\vec{k} = \langle ca_1, ca_2, ca_3 \rangle$.
-
The dot or scalar product is a fundamental operation between two vectors. It produces a scalar quantity that represents the projection of one vector onto another. The dot product is the sum of the products of their corresponding components: $\vec{A}·\vec{B} = \sum a_ib_i = a_1b_1 + a_2b_2 + a_3b_3.$, e.g. $\vec{A}·\vec{B} = \sum a_ib_i = \langle 2, 2, -1 \rangle \cdot \langle 5, -3, 2 \rangle = (2 \cdot 5) + (2 \cdot -3) + (-1 \cdot 2) = 10 - 6 - 2 = 2.$
Geometrically, it is the product of their magnitudes multiplied by the cosine of the angle $\theta$ between them, $\boxed{\vec{A} \cdot \vec{B} = \vert{}\vert{}\vec{A}\vert{}\vert{} \cdot \vert{}\vert{}\vec{B}\vert{}\vert{} \cos(\theta)}$
-
The projection of $\vec{a}$ onto $\vec{b}$ is $proj_{\vec{b}}\vec{a} = \frac{\vec{a}·\vec{b}}{||\vec{b}||^2}\vec{b}$.
-
The cross product, denoted by $\vec{A} \times \vec{B}$, is a binary operation on two vectors in three-dimensional space. It yields a new vector that is perpendicular (orthogonal, at a right angle) to both original vectors and has a magnitude equal to the area of the parallelogram formed by the two input vectors.
The cross product $\vec{A}x\vec{B}$ can be computed using the determinant of a $3 \times 3$ matrix formed by the standard basis vectors ($\hat{\mathbf{i}}, \hat{\mathbf{j}}, \hat{\mathbf{k}}$) and the components of the two vectors: $\vec{A} \times \vec{B} = det(\begin{smallmatrix} \hat{\mathbf{i}} & \hat{\mathbf{j}} & \hat{\mathbf{k}} \\\ a_1 & a_2 & a_3\\\ b_1 & b_2 & b_3\end{smallmatrix}) =|\begin{smallmatrix}a_2 & a_3\\\ b_2 & b_3\end{smallmatrix}|\vec{i}-|\begin{smallmatrix}a_1 & a_3\\\ b_1 & b_3\end{smallmatrix}|\vec{j}+|\begin{smallmatrix}a_1 & a_2\\\ b_1 & b_2\end{smallmatrix}|\vec{k}$.
Example: If $\vec{A} = \langle 1, 2, 3 \rangle$ and $\vec{B} = \langle 4, 5, 6 \rangle$: $\vec{A} \times \vec{B} = \begin{vmatrix} \hat{\mathbf{i}} & \hat{\mathbf{j}} & \hat{\mathbf{k}} \\ 1 & 2 & 3 \\ 4 & 5 & 6 \end{vmatrix} = (2\cdot 6 - 3\cdot 5)\hat{\mathbf{i}} - (1\cdot 6 - 3\cdot 4)\hat{\mathbf{j}} + (1\cdot 5 - 2\cdot 4)\hat{\mathbf{k}} = -3\hat{\mathbf{i}} + 6\hat{\mathbf{j}} - 3\hat{\mathbf{k}} = \langle -3, 6, -3 \rangle$
Matrices offers an efficient way for solving systems of linear equations. Utilizing matrices, we can represent these equations more concisely and conveniently. For instance, consider the system of equations:
$\begin{cases}
x + y + z = 7 \\
3x -2y -z = 4 \\
x + 6y + 5z = 24
\end{cases}$
This can be written in matrix form as: A · X = U where: $A = \bigr(\begin{smallmatrix}1 & 1 & 1\\\ 3 & -2 & -1\\\ 1 & 6 & 5\end{smallmatrix}\bigl), X = \bigr(\begin{smallmatrix}x_1\\ x_2\\ x_3\end{smallmatrix}\bigl), B = \bigr(\begin{smallmatrix}7\\\ 4\\\ 24\end{smallmatrix}\bigl)$.
A system of $n$ linear equations with $n$ variables can be written in matrix form as $AX = B$:
- Coefficient Matrix ($A$): An $n \times n$ matrix containing the variable coefficients.
- Variable Vector ($X$): An $n \times 1$ column vector containing the unknown variables $\begin{pmatrix} x_1 \\ x_2 \\ \vdots \\ x_n \end{pmatrix}$.
- Constant Vector ($B$): An $n \times 1$ column vector containing the right-hand side values.
Conditions for Invertibility
For a square matrix $A$ over a field (such as $\mathbb{R}$ or $\mathbb{C}$):
- $A$ is invertible (non-singular) if and only if $\det(A) \neq 0$.
- If $\det(A) \neq 0$, the unique solution to $AX = B$ is given by $X = A^{-1}B$.
The matrix inverse $A^{-1}$ is calculated as: $\boxed{A^{-1} = \frac{1}{\det(A)} \operatorname{adj}(A)}$ where $\operatorname{adj}(A) = C^T$ is the adjugate matrix (the transpose of the cofactor matrix $C$). The cofactor elements are $C_{ij} = (-1)^{i+j} M_{ij}$, where $M_{ij}$ is the determinant of the $(n-1) \times (n-1)$ submatrix formed by removing both the row $i$ and the column $j$.

Geometric Interpretation (3D Systems)
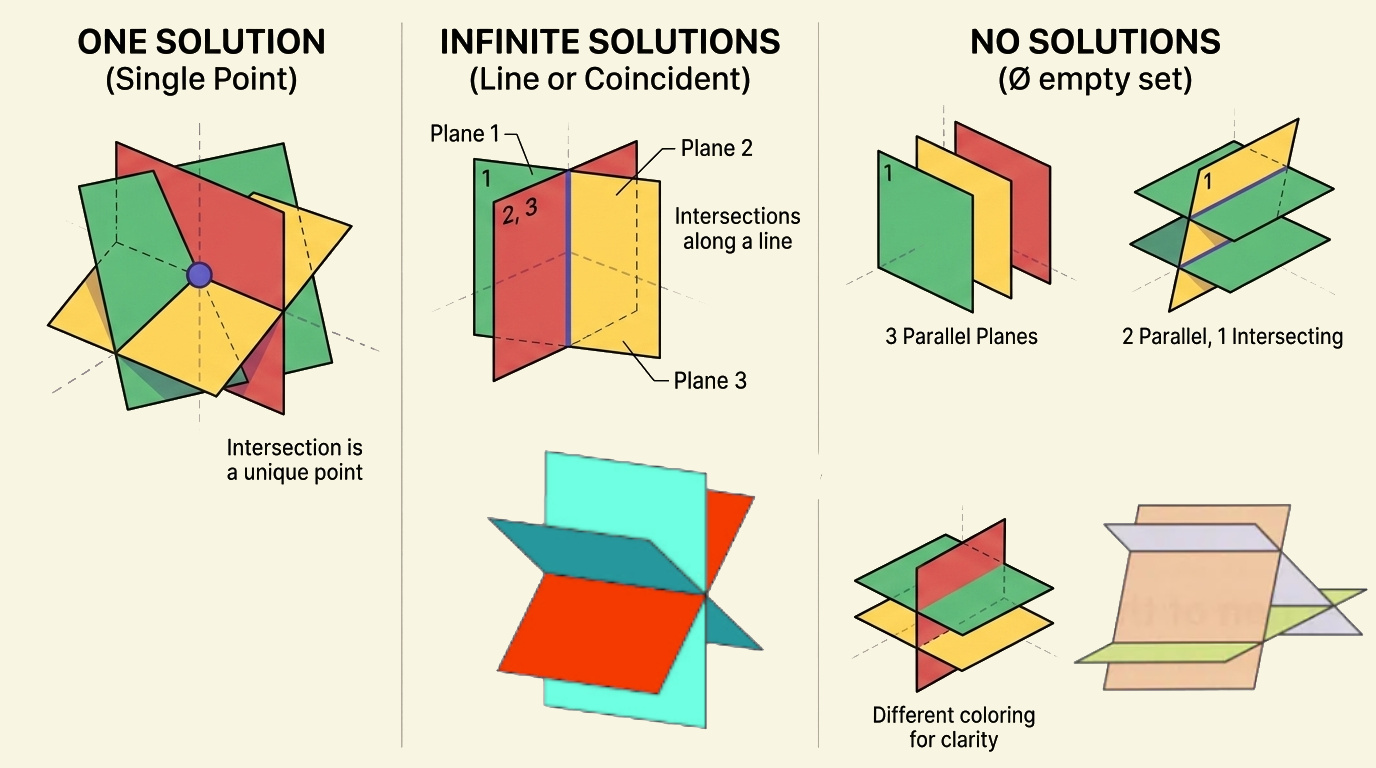
A system of three linear equations with three unknowns or variables represents three planes in a three dimensional space. When solving the system, you are determining how these planes intersect.
The solution to AX = B is given by $X = A^{-1}B$, but this is not always the case. A system of three linear equations in three variables can have one of the following outcomes.
- No solutions. $\det(A) = 0$ (Singular). Row Echelon Form Indicator: Contradiction row ($[0\ 0\ 0 \mid k]$ where $k \neq 0$). The planes do not intersect at a common point, e.g., parallel planes or prism shape.
- Unique solution. $\det(A) \neq 0$ (Non-singular). Row Echelon Form Indicator: Full rank (3 non-zero pivots). The planes intersect at a single point.
- Infinitely many solutions. $\det(A) = 0$ (Singular). Row Echelon Form Indicator: Row of zeros ($[0\ 0\ 0 \mid 0]$) yielding free variables. The planes intersect along a line or overlap entirely as a single plane, indicating dependent equations.
General Ring Theory: Let $R$ be a commutative ring with unity, and $A \in R^{n \times n}$ be a square matrix of order n.
- A is invertible (i.e. there exists $B \in R^{n \times n}$ with $AB = BA = I_n$) if and only if its determinant $\det(A)$ is a unit (invertible element) in R.
- If $R = \mathbb{Q}, \mathbb{R}, \mathbb{C}$ (i.e., a field), then units are precisely the non-zero elements, so 𝐴 is invertible if and only if $\det(A) \neq 0$.
Proof:
(⇒) If A is invertible, then $\det(A)$ is a unit
- Assume: A is invertible, so there exists B with $AB = BA = I_n$.
- Take determinants: $\det(AB) = \det(I_n).$
- By multiplicativity: $\det(AB) = \det(A)\det(B), \quad \det(I_n) = 1.$
- So $\det(A)\det(B) = 1.$ This shows $\det(A)$ has a multiplicative inverse $\det(B)$ in R, hence $\det(A)$ is a unit.
(⇐) If $\det(A)$ is a unit, then A is invertible
- Define the adjugate (or classical adjoint) $\operatorname{adj}(A)$ as the transpose of the cofactor matrix of A. Its entries are polynomials in the entries of A with coefficients in $\mathbb{Z}$, so it makes sense over any commutative ring.
- A standard identity (purely algebraic, no division needed) holds over any commutative ring: $A \cdot \operatorname{adj}(A) = \operatorname{adj}(A) \cdot A = \det(A) I_n.$
- If $\det(A)$ is a unit in R, let $u = \det(A)^{-1}$.
- Multiply the identity by the scalar u: $u A \cdot \operatorname{adj}(A) = u \det(A) I_n = I_n.$
- Rearranging (because u is a scalar, it commutes with the matrix A. You can slide it past A and group it directly with $\operatorname{adj}(A)$ using associativity): $A \cdot \big(u \operatorname{adj}(A)\big) = I_n$, and similarly on the other side, so $B := u \operatorname{adj}(A)$ is a two-sided inverse of A. Hence, A is invertible.
System with a Unique Solution
Consider the system:
$\begin{cases} x + z = 1 \\ x + y = 2 \\ x + 2y + 3z = 3 \end{cases}$
Method A: Algebraic Substitution
- From the first equation, we can express x in terms of z: $x = 1 - z$.
- Substituting $x = 1 - z$ into the second equation, we get: $(1 - z) + y = 2$. Solving for y, we get: $y = 1 + z$.
- Now, we have expressions for x and y in terms of z. Substituting these into the third equation: $(1 - z) + 2(1 + z) + 3z = 3$ ↭[Expand and simplify] $1 -z + 2 +2z +3z = 3$.
Combine like terms: $3 + 4z = 3$. Solving for z: $z = 0$.
Substitute $z = 0$ back to find $x$ and $y$: $x = 1 - 0 = 1, \quad y = 1 + 0 = 1$.
Therefore, the solution to the system is the point (1, 1, 0).
Solving using matrices $X = A^{-1}B$
In matrix form, the system can be written as: $\begin{pmatrix} 1 & 0 & 1 \\ 1 & 1 & 0 \\ 1 & 2 & 3 \end{pmatrix} \begin{pmatrix} x \\ y \\ z \end{pmatrix} = \begin{pmatrix} 1 \\ 2 \\ 3 \end{pmatrix}$.
- Calculate the determinant of A. $\det(A) = a(ei - fh) - b(di - fg) + c(dh - eg) = 1⋅(1⋅3−0⋅2) −0⋅(1⋅3−0⋅1) +1⋅(1⋅2−1⋅1)$
Simplify: $1⋅3 −0 +1⋅(2−1) = 3 + 1 = 4 \quad (\neq 0 \implies \text{Invertible})$.
- Compute the Cofactor matrix C. $C_{ij} = (-1)^{i+j} \times \text{minor}(A_{ij})$ and C = $\Bigl(\begin{smallmatrix}(-1)^{1+1}3 & (-1)^{1+2}3 & (-1)^{1+3}1\\\ (-1)^{2+1}(-2) & (-1)^{2+2}2 & (-1)^{2+3}2\\\ (-1)^{3+1}(-1) & (-1)^{1+2}(-1) & (-1)^{1+3}1\end{smallmatrix}\Bigr) = \Bigl(\begin{smallmatrix}3 & -3 & 1\\\ 2 & 2 & -2\\\ -1 & 1 & 1\end{smallmatrix}\Bigr)$
- Transpose the cofactor matrix to obtain the Adjugate matrix $\operatorname{adj}(A) = C^T = \Bigl(\begin{smallmatrix}3 & 2 & -1\\\ -3 & 2 & 1\\\ 1 & -2 & 1\end{smallmatrix}\Bigr)$.
- Calculate the inverse $A^{-1}$: $A^{-1} = \frac{1}{\text{det}(A)} \times \text{adj}(A) = \frac{1}{4}\Bigl(\begin{smallmatrix}3 & 2 & -1\\\ -3 & 2 & 1\\\ 1 & -2 & 1\end{smallmatrix}\Bigr)$.
- Multiply $A^{-1}$ by B to find $X = A^{-1}B$: $X = \frac{1}{4}\Bigl(\begin{smallmatrix}3 & 2 & -1\\\ -3 & 2 & 1\\\ 1 & -2 & 1\end{smallmatrix}\Bigr)\Bigl(\begin{smallmatrix}1\\\ 2\\\ 3\end{smallmatrix}\Bigr) = \Bigl(\begin{smallmatrix}\frac{3}{4}·1+\frac{1}{2}·2+\frac{-1}{4}·3\\\ -\frac{3}{4}·1+\frac{1}{2}·2+\frac{1}{4}·3\\\ \frac{1}{4}·1+\frac{-1}{2}·2+\frac{1}{4}·3\end{smallmatrix}\Bigr) = \Bigl(\begin{smallmatrix}1\\\ 1\\\ 0\end{smallmatrix}\Bigr)$.
Inconsistent System (No Solution)
$\begin{cases} x - 3y + z = 4 & \text{(i)} \\ -x + 2y - 5z = 3 & \text{(ii)} \\ 5x - 13y + 13z = 8 & \text{(iii)} \end{cases}$
Algebraic Elimination
- Add equations (i) and (ii), (i)+(ii): $-y - 4z = 7 \quad \text{(iv)}$
- Eliminate $x$ by adding $-5\text{(i)}$ to equation (iii): $-5(x - 3y + z) + (5x - 13y + 13z) = -5(4) + 8 \implies 2y + 8z = -12 \quad \text{(v)}$
- Add $2\text{(iv)}$ to equation (v): $2(-y - 4z) + (2y + 8z) = 2(7) + (-12) \implies 0 = 2$.
- Contradiction ($0 = 2$): The system has no solution (inconsistent).
Gaussian Elimination (Augmented Matrix)
- Calculate the determinant of A. $\det(A) = a(ei - fh) - b(di - fg) + c(dh - eg) = 1⋅(2⋅13−(−5)⋅(−13)) −(−3)⋅(−1⋅13−(−5)⋅5) +1⋅(−1⋅(−13)−2⋅5) = 1⋅(−39) −(−3)⋅(−38) +1⋅3 = -39 + 36 + 3 = 0.$
If A is singular (det(A) = 0), we cannot find $A^{-1}$. Instead, we need to use other methods like row reduction to understand the nature of the solutions.
- Convert to Row Echelon Form. A matrix is said to be in row echelon form when all its non-zero rows have a pivot, that is, a non-zero entry such that all the entries to its left and below it are equal to zero.
- Start with the augmented matrix: $\Biggl(\begin{smallmatrix}1 & -3 & 1 &\bigm| & 4\\\ -1 & 2 & -5 &\bigm| & 3\\\ 5 & -13 & 13 &\bigm| & 8\end{smallmatrix}\Biggr)$
- Make the first element of the first row a pivot (which it already is).
- Eliminate the first element (x terms) of the second and third rows by adding suitable multiples of the first row. Add the first row to the second row to eliminate the x term in the second row, $R_2 \to R_2 + R_1$, $\Biggl(\begin{smallmatrix}1 & -3 & 1 &\bigm| & 4\\\ 0 & -1 & -4 &\bigm| & 7\\\ 5 & -13 & 13 &\bigm| & 8\end{smallmatrix}\Biggr)$.
Subtract 5 times the first row from the third row to eliminate the x term in the third row, $R_3 \to R_3 - 5R_1$: $\Biggl(\begin{smallmatrix}1 & -3 & 1 &\bigm| & 4\\\ 0 & -1 & -4 &\bigm| & 7\\\ 0 & 2 & 8 &\bigm| & -12\end{smallmatrix}\Biggr)$.
- Eliminate the second element (y term) of the third row by adding 2 times the second row from the third row, $R_3 \to R_3 + 2R_2$: $\Biggl(\begin{smallmatrix}1 & -3 & 1 &\bigm| & 4\\\ 0 & -1 & -4 &\bigm| & 7\\\ 0 & 0 & 0 &\bigm| & 2\end{smallmatrix}\Biggr)$.
The third row indicates a contradiction $0x + 0y + 0z = 2 \implies 0 = 2$. This confirms that the system of equations is inconsistent and has no solutions.
Dependent System (Infinitely Many Solutions)
$\begin{cases} x + y + z = 2 & \text{(i)} \\ 2x + 2y + 2z = 4 & \text{(ii)} \\ -3x - 3y - 3z = -6 & \text{(iii)} \end{cases}$
Method A: Algebraic Analysis
- $(-2) \times (i)$: $-2x -2y -2z = -4$ (iv)
- $(ii)+(iv)$: $0 = 0$. The firs pairs of equations is indeed the same equation, 2(i) = (ii). The values of x, y, and z that will make the first equation work will also work for the second and vice-versa.
- $3 \times (i) + (iii): 3x + 3y + 3z -3x -3y -3z = 6 - 6 ↭ 0 = 0$. Again, the first and third equations are the same. This three equations have infinitely many solution. The solution is a plane defined by any of the equations, e.g., $x + y + z = 2$.
Gaussian Elimination (Augmented Matrix)
- Start with the augmented matrix:
$\Biggl(\begin{smallmatrix}1 & 1 & 1 &\bigm| & 2\\\ 2 & 2 & 2 &\bigm| & 4\\\ -3 & -3 & -3 &\bigm| & -6\end{smallmatrix}\Biggr)$
- Convert to Row Echelon Form. A matrix is said to be in row echelon form when all its non-zero rows have a pivot, that is, a non-zero entry such that all the entries to its left and below it are equal to zero.
- Make the first element of the first row a pivot (which it already is).
- Eliminate the first element (x terms) of the second and third rows. Subtract 2 times the first row from the second row, $R_2 \to R_2 - 2R_1$: $\Biggl(\begin{smallmatrix}1 & 1 & 1 &\bigm| & 2\\\ 0 & 0 & 0 &\bigm| & 0\\\ -3 & -3 & -3 &\bigm| & -6\end{smallmatrix}\Biggr)$
Add 3 times the first row to the third row, $R_3 \to R_3 + 3R_1$: $\Biggl(\begin{smallmatrix}1 & 1 & 1 &\bigm| & 2\\\ 0 & 0 & 0 &\bigm| & 0\\\ 0 & 0 & 0 &\bigm| & 0\end{smallmatrix}\Biggr)$
- The row echelon form of the matrix indicates that there are two rows of zeros, which means that there are free variables. This implies that the system of equations has infinitely many solutions. The original system reduces to a single equation: x +y +z = 2.
- The general solution to the system is: $\{(2 - y - z, y, z) \mid y, z \in \mathbb{R}\}$ where y and z are free variables, so it represents a plane in a three-dimensional space.
Homogeneous system of linear equations
Definition: A homogeneous system of linear equations is a set of linear equations where all the constant terms a(the values on the right side of the equals sign) are exactly zero. In other words, the system looks like this:
$\begin{cases} a_{11}x_1 + a_{12}x_2 + \dots + a_{1n}x_n = 0 \\ a_{21}x_1 + a_{22}x_2 + \dots + a_{2n}x_n = 0 \\ \dots \\ a_{n1}x_1 + a_{n2}x_2 + \dots + a_{nn}x_n = 0 \end{cases}$
Such a system always has at least one guaranteed solution: the zero vector $(0, 0, \dots, 0)$, also know as the trivial solution. This is because substituting zeros for all variables satisfies every equation in the plane.
If we express this as a matrix equation $AX = 0$:
- Unique Solution: If the determinant of the coefficient matrix is non-zero ($\det(A) \neq 0$), the matrix is invertible. The only solution is the trivial one: $X = A^{-1} \cdot 0 = 0$.
- Infinite Solutions: If $\det(A) = 0$, the matrix is singular. This means the columns (or rows) are not linearly independent —at least one equation is redundant— and the system has infinitely many solutions.
Geometrically, a linear equation with three variables represents a plane in 3D space. Because the constant in a homogeneous system is zero, every plane passes exactly through the origin $(0, 0, 0)$.
Solved exercises
$\begin{cases} x + z = 0 \\\ x + y = 0 \\\ x + 2y +3z = 0 \end{cases}$
(0, 0, 0) is a trivial solution, $\det(\begin{smallmatrix}1 & 0 & 0\\\ 1 & 1 & 0\\\ 1 & 2 & 3\end{smallmatrix}\bigl) = a(ei−fh)−b(di−fg)+c(dh−eg) = 1 (1 \cdot 3− 0 \cdot 2)− 0(1 \cdot 3 − 0 \cdot 1) +0(1 \cdot 2 −1 \cdot 1)=3 \neq 0 ⇒ (0, 0, 0)$ is the only solution.
Solved exercises
- Let A = $(\begin{smallmatrix}1 & 3 & 2\\\ 2 & 0 & -1\\\ 1 & 1 & 0\end{smallmatrix}\bigl)$.
- First, we calculate $\det(A) = 2$.
- Because the determinant is non-zero, $A$ is invertible.
- Let’s calculate the inverse $A^{-1}$ efficiently using cofactors and the adjugate (transpose) matrix: $A^{-1} = \frac{1}{\det(A)} \text{Adj}(A) = \frac{1}{2} \begin{pmatrix}1 & 2 & -3 \\ -1 & -2 & 5 \\ 2 & 2 & -6\end{pmatrix}$
- If we need to solve the non-homogeneous system $\begin{cases} x + 3y + 2z = 1 \\\ 2x -z = -2 \\\ x +y = 1 \end{cases}$.
- Matrix form, $AX = B$ where $B = \begin{pmatrix}1 \\ -2 \\ 1\end{pmatrix}$, we multiply both sides by the inverse: $X = A^{-1}B = \frac{1}{2} \begin{pmatrix}1 & 2 & -3 \\ -1 & -2 & 5 \\ 2 & 2 & -6\end{pmatrix} \begin{pmatrix}1 \\ -2 \\ 1\end{pmatrix} = \frac{1}{2} \begin{pmatrix}-6 \\ 8 \\ -8\end{pmatrix} = \begin{pmatrix}-3 \\ 4 \\ -4\end{pmatrix}$
- Find the value of $c$ where the matrix $M$ is not invertible (singular).
$M = \begin{pmatrix}1 & 3 & c \\ 2 & 0 & -1 \\ 1 & 1 & 0\end{pmatrix}$
- A matrix is singular when its determinant is zero.
- Let’s calculate $\det(M)$ using cofactor expansion along the top row: $\vert{}M\vert{} = a_{11}(a_{22}a_{33} - a_{23}a_{32}) - a_{12}(a_{21}a_{33} - a_{23}a_{31}) + a_{13}(a_{21}a_{32} - a_{22}a_{31}) = 1(0\cdot0 - (-1)\cdot1) - 3(2\cdot0 - (-1)\cdot1) + c(2\cdot1 - 0\cdot1)$
$\vert{}M\vert{} = 1(1) - 3(1) + 2c = -2 + 2c$.
- For the matrix to be singular, set the determinant to zero: $-2 + 2c = 0 \implies 2c = 2 \implies c = 1$
- The matrix $M$ is not invertible when $c = 1$.
- Given the matrix M = $(\begin{smallmatrix}1 & 3 & 1\\\ 2 & 0 & -1\\\ 1 & 1 & 0\end{smallmatrix}\bigl)$, we need to solve the homogeneous system MX = 0, which translates to the system of equations:
$\begin{cases} x + 3y + z = 0 (i)\\\ 2x -z = 0 (ii)\\\ x +y = 0 (iii)\end{cases}$
- The trivial solution (x, y, z) = (0, 0, 0) always satisfies a homogenous system of linear equations. Now let’s explore if there are other solutions.
- If we multiply the third equation by 3, $3 \times (iii)$, we get $3x + 3y = 0$ and then, subtract it to the second equation ($3 \times (iii) -(ii) = (i)$): $x + 3y +z = 0$, that is, the first equation. Therefore, the first equation can be derived as a linear combination of the other two equations, indicating that the system is dependent ⇒ the system of equations have infinitely many solutions.
- From (iii): $x = -y$. Substitute x = -y into (ii): $2x -z = 0 \implies 2(-y)-z = 0 \implies -2y -z = 0 \implies z = -2y$. So every solution has the form $(x, y, z) = (-y, y, -2y)$ where y is a free parameter.
- If you like a parameter 𝑡, you can write: $(x, y, z) = t(-1, 1, -2)$.
Geometric interpretation
Furthermore, calculating a solution can be viewed through the lens of vector dot products. The system $MX = 0$ can be rewritten as a series of dot products between the variables and the coefficients: $\langle x, y, z \rangle \cdot \langle 1, 3, 1 \rangle = 0$, $\langle x, y, z \rangle \cdot \langle 2, 0, -1 \rangle = 0$, and $\langle x, y, z \rangle \cdot \langle 1, 1, 0 \rangle = 0$
if the dot product between a pair of vectors is zero, then the two vectors are orthogonal. Thus, finding the solution vector X means finding a vector that is orthogonal to every row vector of matrix M. This solution set forms the null space of M (The null space of a matrix M is the set of all solutions to the homogeneous equation $M \cdot X = 0$).
As we already know, the cross product of two non-collinear vectors gives a vector perpendicular to the plane determined by the vectors, and therefore, to find the solution $\langle x, y, z \rangle$ -taking into consideration the (iii) equation is l.d of (i) and (ii), hence redundant-, we take the cross product of $ \langle 1, 3, 1 \rangle$ and $\langle 2, 0, -1 \rangle$. In other words, we can find the line of intersection by taking the cross product of the normal vectors from the two independent planes:
v = $(\begin{smallmatrix}\vec{i} & \vec{j} & \vec{k}\\\ 1 & 3 & 1\\\ 2 & 0 & 1\end{smallmatrix}\bigl) = \langle -3, 3, -6 \rangle$. So, any scalar multiple of this vector is also a solution to the system. The line of solution (which passes through O(0, 0, 0) and contains the vector $\vec{N}= \langle -3, 3, -6 \rangle $) has parametric form $x = -3t, y = 3t, z = -6t$.
Verification via Gaussian Elimination
- Formed the Augmented Matrix: $\begin{pmatrix}1 & 3 & 1 &\bigm| &0\\\ 2 & 0 & -1 &\bigm| & 0\\\ 1 & 1 & 0&\bigm| &0\end{pmatrix}$
- Row Reduction to Row Echelon Form We will use Gaussian elimination to simplify this matrix.
- Eliminate x from rows 2 and 3 $R_2 = R_2 - 2R_1$: $\begin{pmatrix}1 & 3 & 1 &\bigm| &0\\\ 0 & -6 & -3 &\bigm| & 0\\\ 1 & 1 & 0&\bigm| &0\end{pmatrix}$
$R_3 = R_3 - R_1$: $\begin{pmatrix}1 & 3 & 1 &\bigm| &0\\\ 0 & -6 & -3 &\bigm| & 0\\\ 0 & -2 & -1&\bigm| &0\end{pmatrix}$
- Use row 2 to eliminate y from row 3, $R_3 = R_3 - \frac{1}{3}R_2$: $\begin{pmatrix}1 & 3 & 1 &\bigm| &0\\\ 0 & -6 & -3 &\bigm| & 0\\\ 0 & 0 & 0&\bigm| &0\end{pmatrix}$.
- Hence, the last equation is l.d. of the other two, there are infinitely many solutions.
- Solve the Reduced System: From Row 2: $-6y - 3z = 0 \implies z = -2y$
Substituting $z = -2y$ back into Row 1: $x + 3y + (-2y) = 0 \implies x + y = 0 \implies x = -y$
This matches our earlier parametric answer! If we set $y = 3t$, then $x = -3t$ and $z = -6t$.
Bibliography
This content is licensed under a Creative Commons Attribution-NonCommercial-ShareAlike 4.0 International License and is based on MIT OpenCourseWare [18.01 Single Variable Calculus, Fall 2007].
- NPTEL-NOC IITM, Introduction to Galois Theory.
- Algebra, Second Edition, by Michael Artin.
- LibreTexts, Calculus. Abstract and Geometric Algebra, Abstract Algebra: Theory and Applications (Judson).
- Field and Galois Theory, by Patrick Morandi. Springer.
- Michael Penn, Andrew Misseldine, blackpenredpen, and MathMajor, YouTube’s channels.
- Contemporary Abstract Algebra, Joseph, A. Gallian.
- MIT OpenCourseWare, 18.01 Single Variable Calculus, Fall 2007 and 18.02 Multivariable Calculus, Fall 2007, YouTube.
- Calculus Early Transcendentals: Differential & Multi-Variable Calculus for Social Sciences.



